Search This Blog

Wednesday, September 16, 2026

Fed Hikes: Then What?

 Our title, “Fed Hikes,” is a bit presumptuous, but with Fed Funds futures assigning a 90% chance of a hike this afternoon, it’s likely a done deal. Instead of debating whether the Fed hikes, the more useful question for investors is: what comes next? Three things from Wednesday’s FOMC meeting will likely put us in a better place to answer that.

Assuming the Fed releases its Summary of Economic Projections (SEP), aka dot plots, it will likely be the most important tell. Watch the median dots and outlying dots regarding 2026 projections on where Fed Funds will end the year. A tight cluster of dots signals conviction among the members, whereas a wide spread signals division. With only 2 meetings left, we suspect the median will be near one more hike, assuming they raise rates today.

Second, watch the FOMC statement’s balance of risk language. If the inflation tone softens, today’s expected hike could be a single defensive move rather than the start of a series of Fed hikes. Further, increased concerns about labor conditions could warrant caution from the Fed.

Third, listen for how Warsh frames the decision in his press conference. Instead of saying “one and done” or “the first of several,” we suspect he will say future policy decisions will be predicated on incoming economic data.

Since 1994, the Fed has conducted six hiking cycles, as we share below. Five of them ran for years and included six hikes or more. The exception is March 1997, when Greenspan hiked once, and then cut in 1998. Every other modern cycle kept going well beyond the first move. Despite history, given that real rates are starting from an historically high point, we suspect the number of hikes in this cycle will be limited.
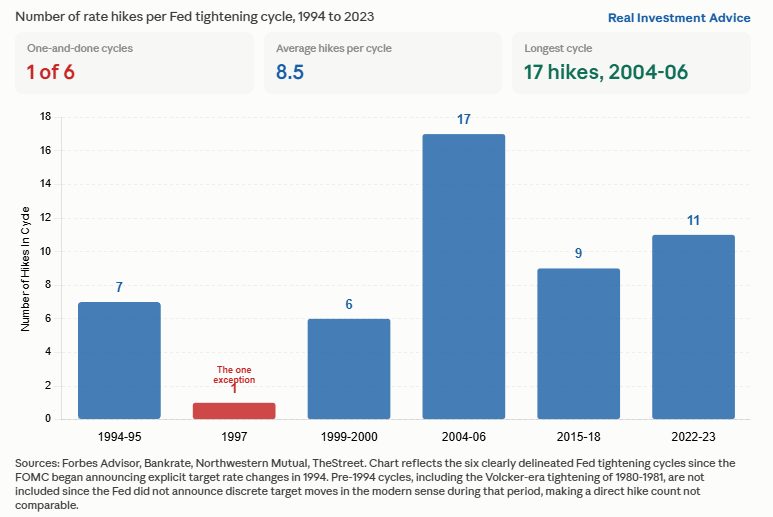
prior rate hike cycles

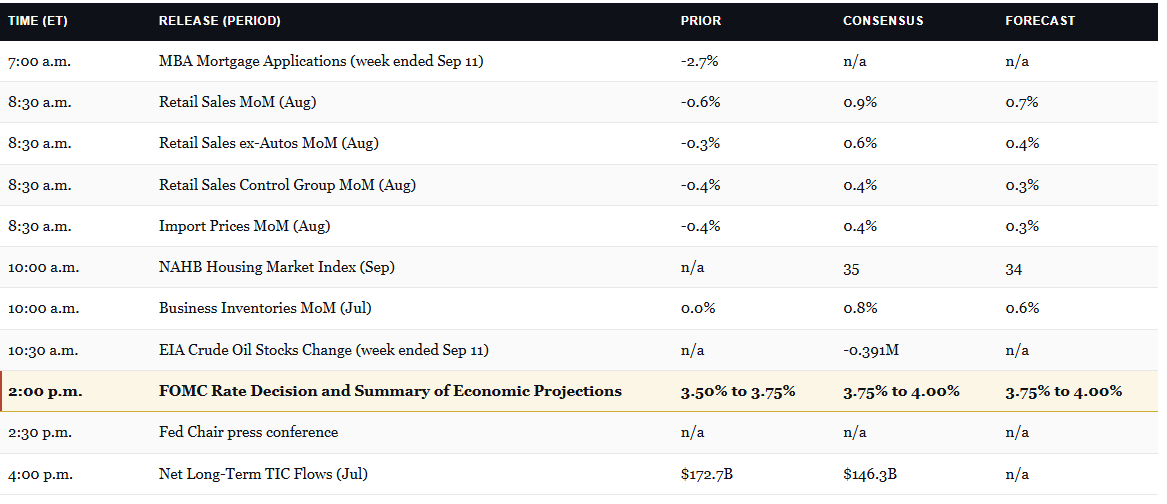
What To Watch Today

Earnings

Earnings Calendar

Economy

Economic Calendar

Market Trading Update

Yesterday, we worked through whether the AI capex backlog actually bends when the frontier labs start talking about slowing down. Today the tape handed us a cleaner question about rising yields and equity returns. The 10-year Treasury pushed through 5% on Monday and traded at 5.01% Tuesday morning, the highest level since July 2007.

That number matters because Wall Street told us it would. Bloomberg’s Markets Pulse survey of 122 participants, conducted September 8th through the 10th, asked how high yields would need to go before year-end to trigger a 10% correction. Nearly 78% put the answer between 5.00% and 5.75%. Just 1.6% thought anything below 5% would do it.
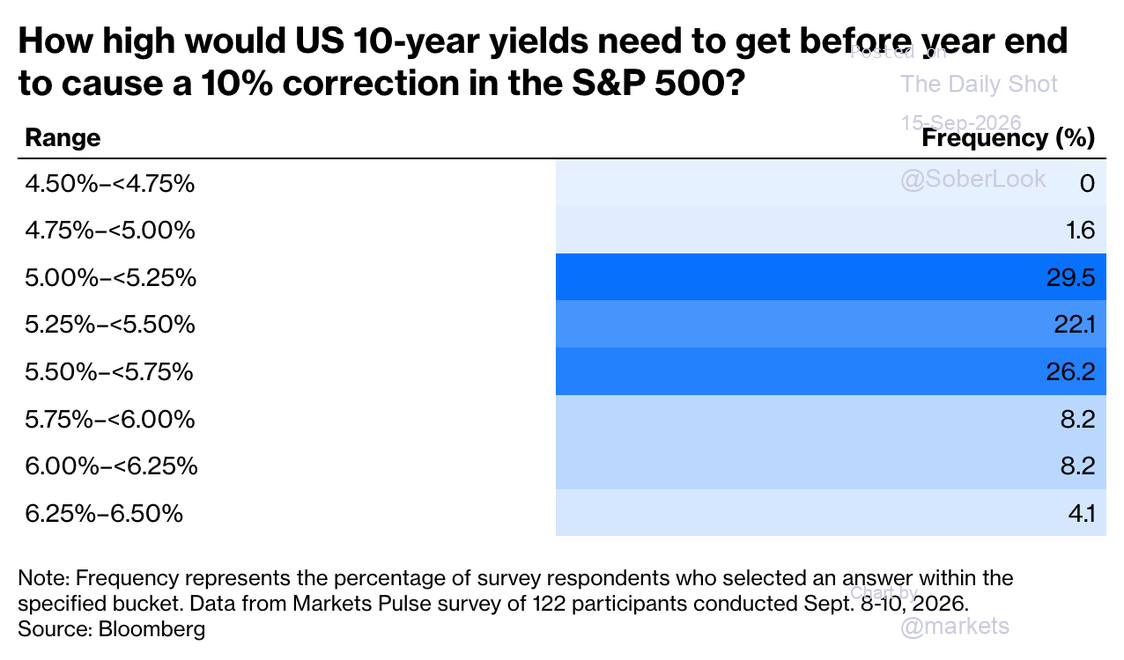
How high would US 10-year yields need to get before year end to cause a 10% correction in the S&P 500?

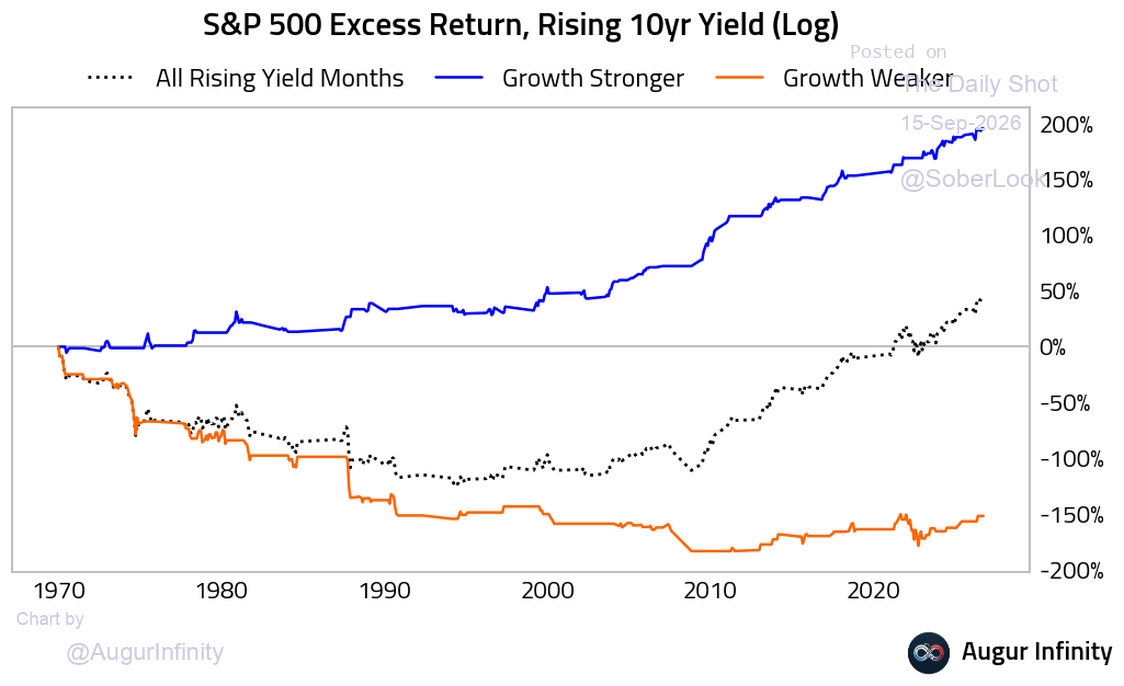
Here’s what the consensus misses. Rising yields did punish stocks, but mostly in the first half of the sample. The relationship broke down right around the time the 10-year fell under 5% and stayed there. So the line everyone is watching marks where the modern data set begins, not where equities break. Such is the trouble with threshold thinking. It mistakes a historical coincidence for a law of markets.
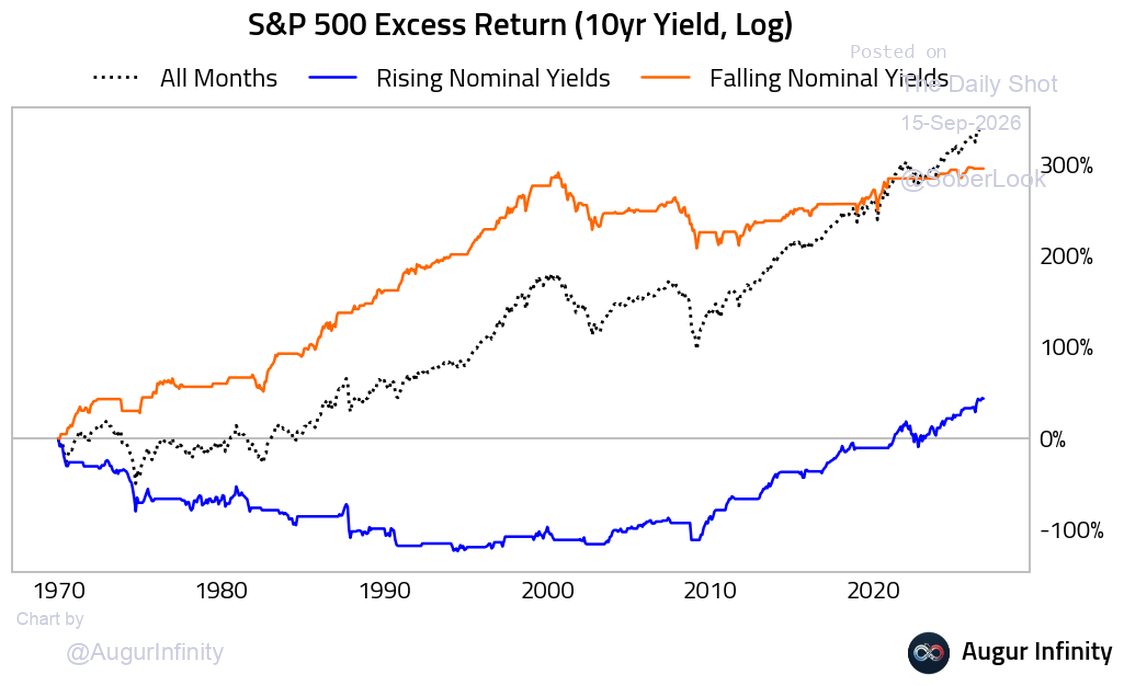
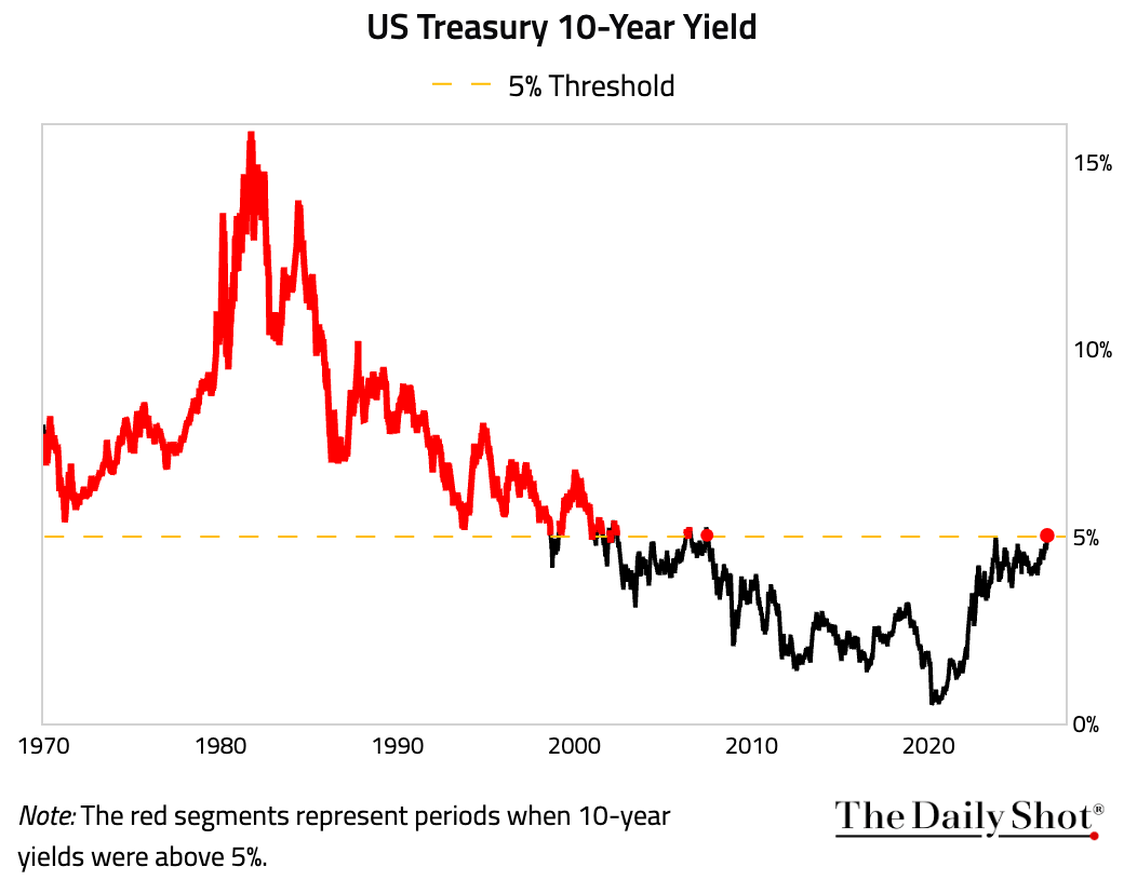
excess_by_yield_env_nominal

The real variable isn’t the rate. Its growth. Split the rising-yield months by whether growth was strengthening or weakening, and the outcomes separate violently. Stronger growth with rising yields delivered a large positive excess return over cash. Weaker growth with rising yields delivered a deeply negative one. Same rates. Opposite results.
excess_by_yield_env_nominal

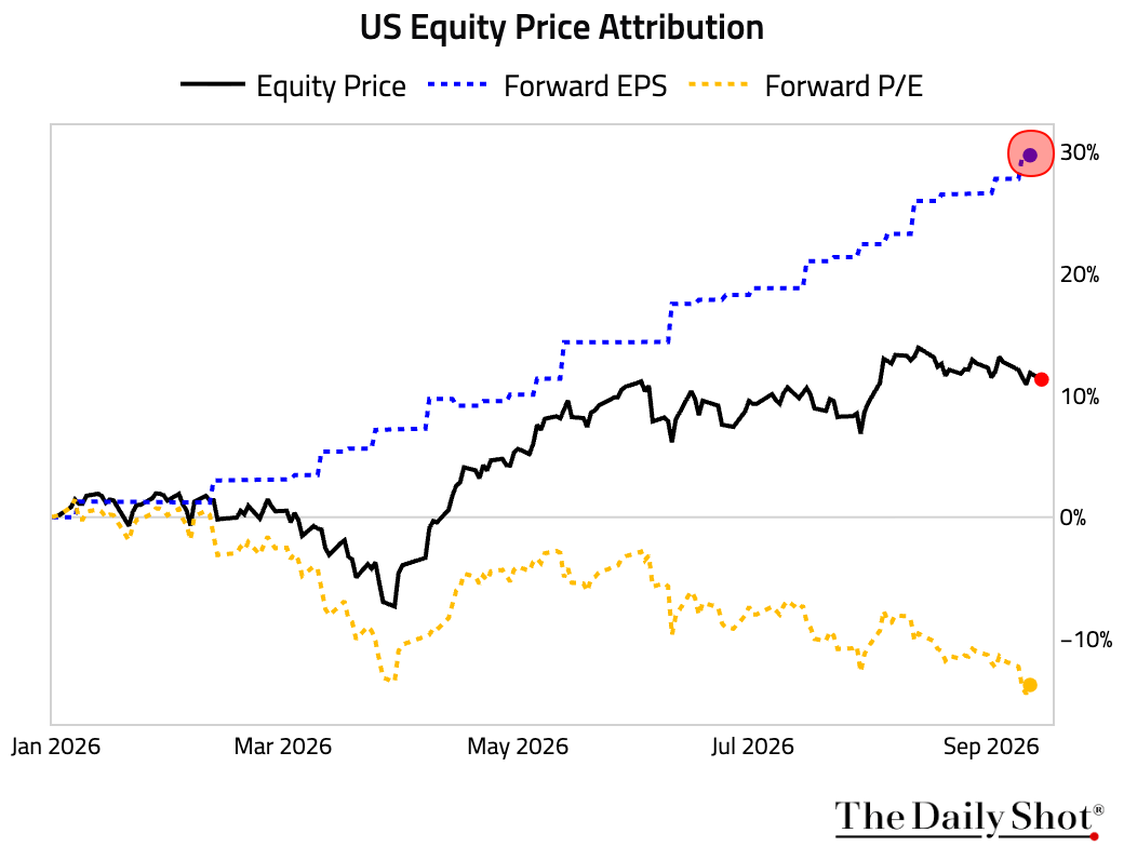
The multiple has already paid its toll. Forward earnings are up roughly 30% this year while the forward P/E compressed about 13.5%, from north of 23 down near 19. The index is up 11.6% year to date on EARNINGS, not on multiple expansion. The bond bears will tell me the deficit makes this cycle different. Maybe. But the de-rating they keep forecasting has largely already happened.
Rate Expectations and Stock Valuations

The sector tape mostly confirms the map. Since the 10-year bottomed at 3.97% on February 27th, energy has run 15.4% against the index’s 10.9%, while utilities lost 12.4% and staples 6.2%. Financials only matched the market, so the rate trade isn’t as clean as the textbook says.

The S&P closed below its 50-day moving average near 7,606 yesterday. That line is the trade into Wednesday’s Fed decision. If it holds, this stays a repricing. If markets fall further, the next add point is the 200-day near 7,163, not before.

Watch the growth data, not the yield print. Rates don’t end bull markets. Recessions do.

This Is Not 2022

With Fed hikes on the table, we hear some pundits harkening back to the last tightening cycle, which started in 2022. The setup then and now is nothing alike.

In 2022, the Fed was grossly offside. Inflation ran near 9%, and the real 10-year yield was negative when hikes began. The Fed was running extremely accommodative policy despite surging prices. They ultimately hiked 11 times in sixteen months, the most aggressive tightening since the 1980s. The bond market repriced violently because the Fed started so far behind the curve.

Today’s starting point is the opposite. The real 10-year real yield sits near 2.50%, the highest level in almost twenty years, and the yield curve has flattened meaningfully, both signals that financial conditions are already restrictive. This isn’t the Fed playing catch-up; it’s the Fed worried about its inflation-fighting credibility, much of which dates back to 2020-2022, when it botched monetary policy.

The inflation level and its drivers today versus 2022 are also vastly different. Today’s price pressures trace largely to the Iran conflict, oil, energy, and related goods. We are in a geopolitical supply shock, not the 2022 broad demand-supply mismatch born of pandemic stimulus and broken global supply chains. Geopolitical shocks reverse quickly once the underlying conflict de-escalates. Supply-demand mismatches take much longer.

Investors bracing for a prolonged 2022-like hiking cycle are fighting the last war.

2022 versus today

Tweet of the Day

fed rate hikes projections
https://realinvestmentadvice.com/resources/blog/fed-hikes-then-what/

Has The Bond Market Already Done The Fed’s Job?

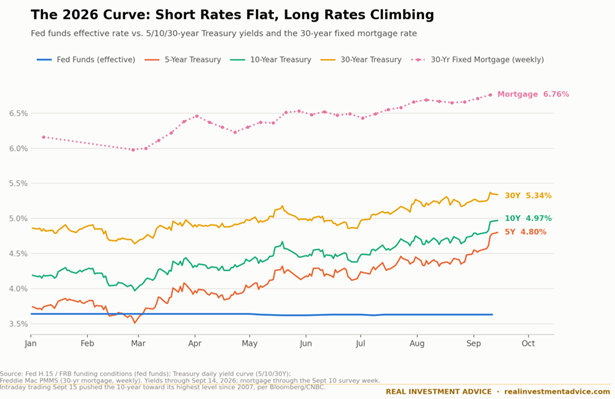
 We publish this article hours before the Fed updates monetary policy at its September 16, 2026, FOMC meeting. Prior to its decision, the Fed has kept the Fed Funds rate steady even as inflation runs stubbornly above target. At the same time, longer-term bond yields have risen appreciably and, in the process, are tightening financial conditions. The 10-year Treasury just surpassed 5%, and mortgage rates, corporate borrowing costs, and equity discount rates have all risen similarly. The combination of no Fed tightening but relatively significant market tightening raises a question. If long-maturity yields are weighing on economic activity, has the bond market already done the Fed’s job?

bond yields rates

The answer is complicated. The short and long ends of the yield curve impact the economy and inflation differently; accordingly, they are not necessarily substitutes for each other. Both impact GDP and inflation, but through separate channels and timelines.

What The Long End Impacts

The 5-year, 10-year, and 30-year bond yields influence personal consumption, corporate capex plans, and the pricing of assets valued off a moderate or long stream of future cash flows.

Consider the following important sources of economic activity:

Housing

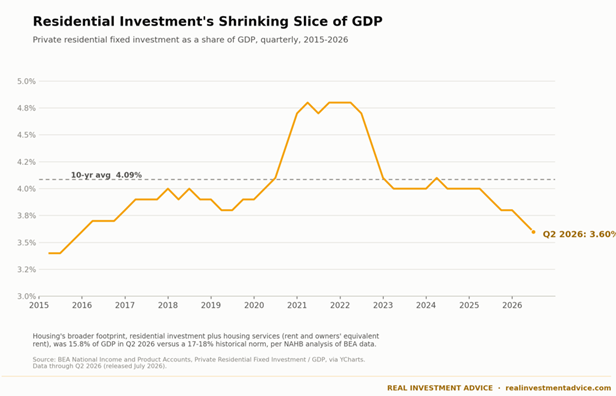
The 30-year mortgage rate closely tracks the 10-year Treasury plus a spread. With the 10-year yield at 5.00% and mortgage rates near 7.00%, new and existing home sales, buyer demand, and housing turnover are depressed. As a result, residential fixed investment as a percentage of GDP has fallen from nearly 5% in late 2021 to 3.6% today as mortgage rates more than doubled. 

housing and gdp

Corporate financing

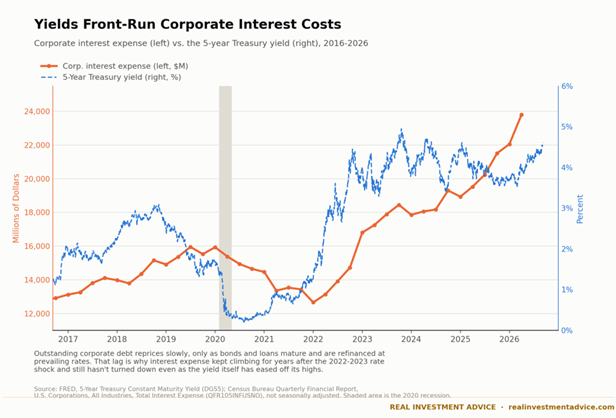
Corporate bond issuance is priced as a spread to Treasury yields. Thus, higher Treasury yields raise borrowing rates and increase corporate interest expense. The impact lags, as shown in the graph below. Higher yields also raise project hurdle rates for capital expenditures.

Higher interest costs reduce profits, often leading executives to cut expenses, including payroll. At the same time, higher project hurdle rates often cause firms to delay or reduce capex. In both cases, higher rates dampen economic activity over time.

corporate interest costs

It’s worth adding that higher rates today may have a greater impact than in the past because corporations borrowed extensively when rates were historically low in 2020 and 2021. A good portion of cheap debt is maturing over the next two years. Refinancing it at much higher rates will have a greater impact on interest expenses than in the past, even if Treasury yields stay at current levels or decline.

Auto Loans

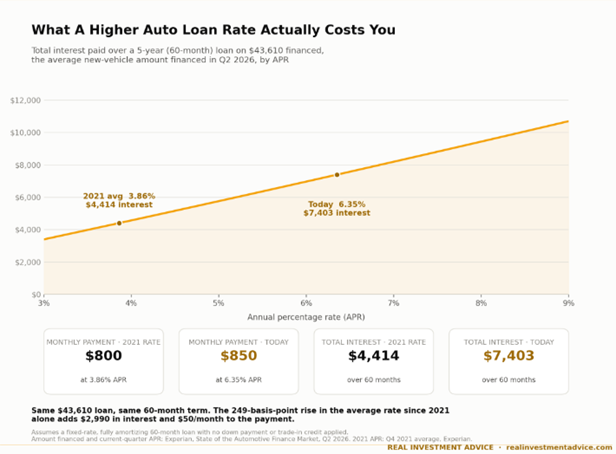
New and used auto loan rates price mainly off the three- to seven-year part of the Treasury curve, which matches the loan’s duration. These short- to intermediate-term yields are up nearly 100 basis points since their late-February low, pushing auto financing costs higher even though the Fed hasn’t raised rates. Auto sales account for approximately 5% of GDP.

auto rates affordability

Equity valuations

Equities are long-duration assets, with cash flow duration estimated at roughly 20 or more years on average. A higher long-term discount rate compresses fair-value calculations. In turn, lower valuations, if they weigh on stock prices, can hurt consumer sentiment through the psychological wealth effect. It’s debatable whether higher yields have impacted equity markets yet, but regardless, the odds of them negatively affecting stocks rise as bond yields rise.  

Federal Interest Expense

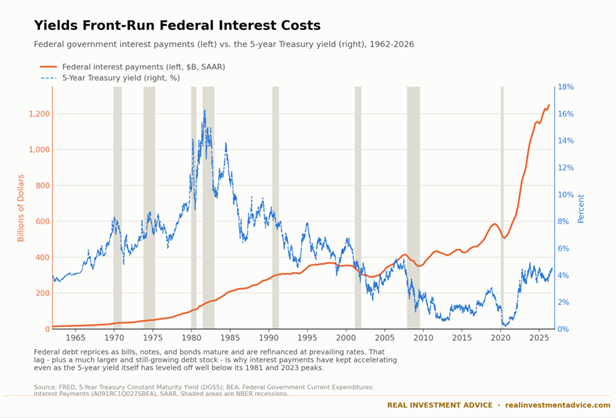
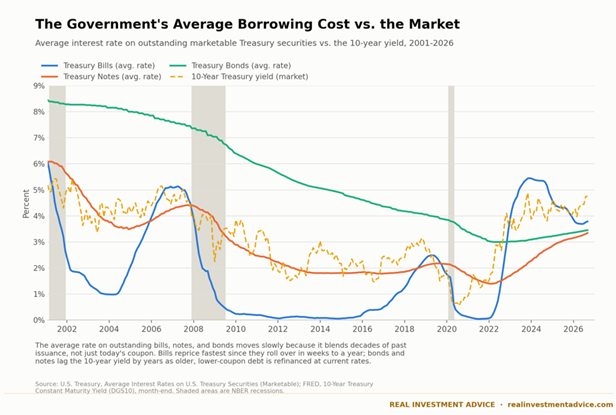
Higher yields raise the government’s borrowing costs, but that increase in expense takes time, as most debt is set at lower rates and only resets when it matures. The first graph shows the sharp increase in the government’s interest payments since 2020. The following graph shows the lag between changes in rates and changes in the government’s average interest rate. Note that longer-term bonds have a much longer lag than bills.

federal interest rate and expense
government borrowing costs interest expense

The important takeaway is that as the government demands more money to finance its debts, it crowds out financing for consumers and corporations, ultimately raising their borrowing costs.

Higher Long Rates Are A Headwind

While those economic sectors and assets, and many others we don’t mention, are negatively impacted by higher long-term rates, none are a direct inflation channel. Rising long-term yields cool the economy by discouraging borrowing and spending, and lower demand or weak sentiment eventually feeds through to prices, but the diffusion is slow.

What The Short End Impacts

The Fed Funds rate and short-term Treasury bills govern different financial channels that tend to influence inflation more directly and quickly than longer-term yields.

Consumer Revolving Credit

Credit card rates, home equity loans, and floating-rate auto and small business loans are typically priced off the Prime Rate, which is the Fed Funds rate plus a fixed spread. A change in the Fed Funds Rate, and thus the Prime Rate, hits household and business cash flows within a billing cycle and directly alters consumption decisions with immediate effects on both prices and economic activity.

Bank Net Interest Margin And Credit Supply

Banks tend to fund their long-term assets, like loans and mortgages, with short-term liabilities. Short-term rates, along with the shape of the yield curve, determine lending profitability, i.e., a bank’s net interest margin. Banks are more willing to extend credit when lending margins are high.  Thus, an increase in the Fed Funds rate, which often flattens the yield curve and, by default, banking profitability, can materially reduce lending activity.

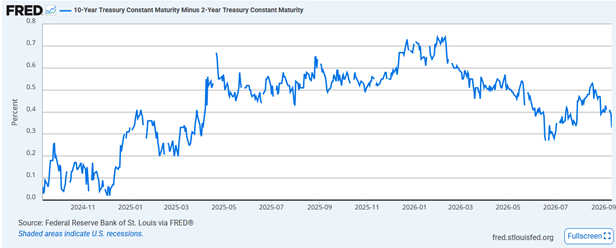
As we show below, the yield curve is flattening (tightening net interest margins) as the market anticipates rate hikes.

treasury bond yield curve

Savings And Cash Yields

Money market and short Treasury Bill yields determine what households and businesses earn on cash. Those rates shape the propensity to spend versus hold cash. This can be a fast-moving channel that works opposite the slow equity wealth effect.  Higher yields incentivize consumers to save rather than spend, thus slowing economic activity.

Inflation Expectations And Fed Credibility

This may be the most important factor in answering the question of “has the market done the Fed’s job” question. The Fed Funds rate is the primary tool the FOMC uses to manage monetary policy. Consumers, businesses, and investors are watching it closely today as a credibility signal of whether the central bank is committed to its 2% inflation target.

A tightening bond market, as we have, can restrain growth but says little about the Fed’s resolve. Only the Fed’s policy actions on the Fed Funds rate can do that.

Federal Reserve Governor Christopher Waller made a similar point in comments this month. He said policy is:

currently only slightly restricting aggregate demand,” and that “it may not take much acceleration in inflation to nudge me into supporting tighter policy.”

That describes someone who views the front end, not the back end, of the yield curve as the inflation-credibility lever.

Summary

Long-term yields impact the economy and inflation but often with a decent lag. Thus, the impact of higher yields hasn’t largely been felt yet. Short-term rates tend to affect growth and inflation more immediately. All that said, while stubbornly high inflation is a big problem and argues for Fed action, the recent inflation uptick and deviation from the downward inflation trend is largely due to the Iranian conflict and higher energy prices.

The Fed Funds rate can’t solve the Iranian oil problem. So, we must ask: Is the price of “restoring inflation credibility” worth it, if higher Fed Funds rates have a very limited impact on inflation but risk meaningful damage to economic activity?

Hiking into a supply shock driven by geopolitical matters could be a big policy error. Accordingly, if they do hike rates, they could likely be followed shortly by rate cuts, an admission of sorts of a policy error. 

https://realinvestmentadvice.com/resources/blog/has-the-bond-market-already-done-the-feds-job/

70% Of Swedes With Non-European Background Supported The Left In Narrow National Election Victory

 Via Remix News,

For years, the right across the West has noted that mass immigration has been a boon for left-wing parties, which are essentially importing a new voting base. Sweden's latest election appears to once again affirm this view, with the left narrowly winning the election, in large part due to their overwhelming support from those with a non-European background in Sweden.

Sweden's 2026 election produced one of the narrowest results in recent memory. With roughly 94.7 percent of votes counted, the center-left opposition holds 176 seats against 173 for the parties backing outgoing Prime Minister Ulf Kristersson.

The left-wing Social Democrats remain the largest party at 28 percent, enough to put Magdalena Andersson in position to try to form a government.

A striking pattern in SVT's VALU exit poll helps explain how the result took shape, with 70 percent of voters of non-European origin backing the left-wing bloc of Social Democrats, Left Party, Greens, and Center.

"VALU shows a very clear political dividing line. Among voters with non-European backgrounds, S, V, MP, and C together receive 70 percent, while the Tidö parties receive 27. This is a voter group whose party sympathies differ sharply from the electorate as a whole - and which therefore has significance for the long-term electoral math," wrote Swedish political scientist and author Daniel Schatz on X.

VALU defines the group as people who themselves, or whose parents, grew up outside Europe. Their votes broke down for the Left at 21 percent, Social Democrats at 38 percent, Greens at 7 percent, and Center at 4 percent.

Before the election, the leader of the right-wing Sweden Democrats, Jimmie Ã…kesson, also wrote that the left's strategy is to gain votes from Swedes with a foreign background even as they lose votes from native ethnic Swedes:

"It's about power. The Social Democrats' decades-long campaign for increased immigration from the Muslim world has never been a coincidence. On the contrary, it seems to be a long-term strategy. The election promise from Magdalena Andersson to grant citizenship to up to 100,000 immigrants, based on the old and undemanding regulatory framework, should be seen in the same light," he wrote.

"When Swedish voters flee the party, you need votes from elsewhere, and mass immigration from the Muslim world then appears to be an attractive way to circumvent the will of the Swedish people," he added.

In 2022, Swedes with a foreign backgroun already attracted around 68 percent of this electorate. Earlier surveys of Muslim voters had placed combined support for the Social Democrats, Left and Greens near 85 percent, with the Social Democrats alone above 61 percent. This slice of the electorate has expanded rapidly over the years.

About 13 percent of eligible voters, close to 1 million people, now have non-European origins, up from just over 3 percent in 2002 and 0.3 percent in 1982.

Many arrived from Muslim-majority countries in the Middle East, Africa and Asia through asylum, family reunification and earlier, more open immigration rules.

Sweden does not record religion in official statistics, yet estimates indicate that Swedish citizens from Muslim-majority countries number in the hundreds of thousands. Together, with other voters of non-European background, they form a reliable base for the left even as much of the rest of the country has shifted toward tighter immigration and crime policies.

Remix News reported on polling already six years ago which showed that a majority of Swedes wanted to tighten immigration substantially. While the native ethnic Swedish population has swung to the right, foreigners have incentives to vote for the left to ensure their families and fellow countrymen can arrive in Sweden unimpeded. Foreigners are also more likely to benefit from social welfare, which left-wing parties promote.

The overwhelming vote for the left from those with a non-European background has been seen across the Western world. In Germany, for instance, the Left Party has proposed giving voting rights to all foreigners who have lived in Germany for five years, regardless of whether they have citizenship. Similar proposals have been put forward by other left-wing parties in the country.

https://www.zerohedge.com/geopolitical/70-swedes-non-european-background-supported-left-narrow-national-election-victory

September 15, 2026 2:14 PM2 min read Why Is Waystar Holdings Stock Gaining

 Healthcare payment software provider Waystar Holdings Corp. (NASDAQ:WAY) is reportedly exploring strategic alternatives, including a potential sale. A deal could take Waystar private just two years after its initial public offering.

Following the media report, the stock jumped nearly 8%.

Waystar Raises 2026 Outlook

Waystar recently reported second-quarter adjusted earnings of 43 cents per share, beating the 40-cent consensus estimate. Revenue of $319.67 million also topped Wall Street expectations of $316.16 million.

The company raised its fiscal 2026 adjusted earnings guidance to $1.61 to $1.70 per share, up from its prior outlook of $1.59 to $1.68. The revised range brackets Wall Street’s $1.64-per-share estimate.

Waystar also raised the low end of its 2026 revenue outlook, forecasting $1.276 billion to $1.294 billion, compared with its previous range of $1.274 billion to $1.294 billion. Wall Street expects $1.284 billion.

William Blair said deal pricing could be a key consideration. Waystar issued shares valued at about $37 to Iodine Software’s private equity owners when it announced that acquisition.

The firm estimates Advent International, Iodine’s largest shareholder, would likely need a potential offer in the low- to mid-$30s per share to support a transaction. It maintains an Outperform rating.

Sale Talks Remain Early

Reuters reported Tuesday that the company hired investment bank Evercore to advise on the process.

The discussions remain at an early stage, according to people familiar with the matter. The plans could change, and Waystar may ultimately decide against a sale.

A potential auction could also test investor appetite for software-focused businesses.

AI Concerns Pressure Shares

The company has positioned itself as a healthcare software company focused on automating administrative workflows.

However, Morgan Stanley analysts said in July that investors had grown increasingly concerned that artificial intelligence would disrupt software companies.

Those concerns, combined with a broader software selloff, have weighed heavily on Waystar shares this year.

https://www.benzinga.com/news/health-care/26/09/61800659/why-is-waystar-holdings-stock-gaining-tuesday

US, Vietnam Firms Set to Announce Deals During To Lam Visit

 US and Vietnamese companies are expected to announce a series of agreements in energy, technology.

https://finance.yahoo.com/markets/stocks/articles/market-chatter-us-vietnam-firms-082219584.html


5 biotechs braving the commercial waters with product launches


A growing number of biotechs are entering the market with newly launched medicines, a pattern indicative of “improving capital markets,” according to Jefferies’ Andrew Tsai.

The lion’s share of medicines on the market belong to Big Pharma—drugmakers worth tens of billions of dollars—but increasingly, smaller players are braving the commercial world.

“We’re seeing an explosion in the number of new product launches by biotech companies,” Graig Suvannavejh, managing director and senior biotech and biopharma analyst at Mizuho Securities, told BioSpace in an email interview. The group has documented “great successes” across the board, though the industry’s track record is by no means perfect.

“Launching drugs is really hard,” he continued, especially with payers “putting in place hurdles and restrictions, making market access to new drugs more challenging.”

Still, there is much to be optimistic about. Many biotechs are “preparing better” for their product launches, building up not just their commercial capacities but also their understanding of patient, physician and payer needs, Suvannavejh said.

There are larger macro factors at play, too, according to Andrew Tsai, managing director at Jefferies. “Broadly speaking, we think that the improving capital markets has helped,” he told BioSpace over email. Jefferies’ analysis of the trends this year so far “suggests that 2026 financing is on pace to reach an all-time high, implying that investors have an appetite to fund assets they think may have a competitive commercial profile.”

A shift in investor attitude may have also helped, Tsai said, however cautioning that he has only anecdotally observed these changes. These days, investors seem to reward companies for early sales beats of recently launched products. This is in contrast to many years ago, when “it was common for investors to ‘short the launch,’” he explained, referring to the investing tactic of actively betting on a drug failing to perform well on the market.

Here, BioSpace looks at five biotechs taking the commercial plunge to find out just how favorable the current markets are to smaller companies launching a drug.

Big Pharma-partnered Protagonist launches two products

Protagonist Therapeutics is having a big year so far. In March, the FDA approved the Johnson & Johnson–partnered IL-23 blocker Icotyde for moderate-to-severe plaque psoriasis, unlocking a market opportunity that Truist Securities estimates could reach $5–10 billion.

Then, late last month, the biotech clinched another regulatory victory for the Takeda-partnered Mimrylo for polycythemia vera. The product could hit another $2 billion in peak sales, Jefferies projected at the time.

Mimrylo’s uptake is too early to assess, but Icotyde has been performing well. During J&J’s second quarter earnings call in July, CEO Joaquin Duato said that Icotyde was off to “significant early launch momentum, with uptake accelerating and performance outpacing competitors at comparable points in their launches.”

While the pharma at the time didn’t provide specific sales figures for Icotyde, Jennifer Taubert, worldwide chairman of J&J’s Innovative Medicine unit, told investors that there were already more than 18,000 prescriptions of the drugs for some 11,000 patients. Psoriasis revenues for Icotyde could reach $1.6 billion by 2028, according to Visible Alpha, a division of S&P Global Market Intelligence.

Protagonist and J&J continue to develop Icotyde, with an eye toward expanding to other immunology indications. The partners are running two Phase 3 studies of the drug in psoriatic arthritis, the first of which is expected to read out later this year, according to the pharma’s Q2 presentation.

Denali Therapeutics’ Hunter syndrome launch exceeds expectations

In March, Denali Therapeutics’ enzyme replacement therapy notched an FDA approval for Hunter syndrome, delivering a much-needed win for the rare disease space that at the time had been battered by a series of negative headlines. Months later, the rare disease news flow remains mixed, but Denali’s drug has continued its victory lap.

The therapy, called Avlayah, made $3.6 million in its first quarter on the market, the California biotech revealed in a second quarter earnings report last month. This pleasantly surprised analysts, who had projected $1.3 million in Q2 sales for Avlayah.

Given the strength of Avlayah’s first three commercial months, Denali estimates net Avlayah revenues to hit $10–12 million in the third quarter, outpacing William Blair’s original forecast of around $6 million, according to an Aug. 7 note. The firm has now bumped that up to $10.7 million in Q3 and $29.3 million for the rest of the year.

What makes Avlayah’s success all the more impressive is that the drug is going up against Takeda’s Elaprase, another enzyme replacement therapy that has a two-decade headstart on the market. Denali’s launch strategy is to entice patients on Elaprase to switch over to Avlayah—an approach that William Blair calls “underappreciated.”

“Denali is well positioned and capitalized to drive switches from Elaprase,” the firm wrote on Aug. 7. By the late 2030s, Avlayah sales could surpass $250 million in the U.S. and reach $1 billion worldwide.

Avlayah is the first new therapy cleared for Hunter syndrome in nearly 20 years and is the first medicine that directly addresses neurologic complications of the disease, the FDA said at the time of the product’s approval.

BridgeBio has upper hand over ATTR adversaries

BridgeBio has more than tripled sales of the transthyretin amyloidosis (ATTR) therapy Attruby in a year.

Attruby revenues hit $222.4 million in the second quarter, compared with $71.5 million during the same period in 2025, the company reported last month. Analysts expect the product will continue on this upward trajectory, hitting blockbuster status this year with sales exceeding $1 billion, according to Jefferies.

Attruby, a drug that stabilizes the transthyretin protein and prevents pathologic misfolding, was approved for ATTR cardiomyopathy (CM) in November 2024. This gave BridgeBio a few months lead over a crucial competitor: Alnylam’s transthyretin silencer Amvuttra, which won regulatory clearance for the treatment of ATTR-CM in March 2025. Alnylam, however, had a leg up as a familiar brand, since Amvuttra’s first approval came in June 2022 for ATTR polyneuropathy.

But with BridgeBio entering the ATTR-CM market, Amvuttra sales underwhelmed, bringing in $1.01 billion worldwide in the second quarter, below the investor consensus of $1.05 billion. Alnylam has also lowered full-year revenue guidance for Amvuttra, from $4.4 billion to $4.7 billion down to $4.2 billion to $4.5 billion.

There appear to be other factors going in BridgeBio’s favor, too. In July, Attruby—alongside the broader stabilizer class more broadly—received a boost when AstraZeneca and Ionis reported a late-stage fail for their antisense oligonucleotide Wainua, which did not significantly improve cardiovascular outcomes in patients with ATTR-CM. Like Alnylam’s Amvuttra, Wainua works by lowering the expression levels of transthyretin. Attruby, on the other hand, binds to the protein and prevents a crucial step in the formation of the disease-causing clumps.

“Peak sales estimates for Attruby may edge higher” after the Wainua failure, Mizuho Securities wrote in a July 9 note.

Axsome’s Auvelity poised for $6B peak with Alzheimer’s agitation expansion

Axsome’s Auvelity first hit the market in 2022 after being approved for major depressive disorder. But in May this year, the non-antipsychotic drug won a key expansion into Alzheimer’s disease agitation—one that Jefferies’ Tsai said could position Auvelity to “capture strong [first-line] market share” in the indication.

Alzheimer’s disease agitation is a largely untapped market, with the only other FDA-approved option being Otsuka and Lundbeck’s antipsychotic Rexulti, Tsai said in an email to BioSpace. Auvelity has key edge over its competition because the product doesn’t have a boxed warning flagging a heightened risk of death in older patients, he said.

This safety advantage “incentivizes adoption by all parties,” Tsai said. Auvelity also doesn’t come with weight gain, anxiety and motor problems, all typical of antipsychotic medications.

Following the launch in Alzheimer’s agitation in June, “we think Auvelity should reach $6B combined peak sales, split between” this indication and major depressive disorder, Tsai told BioSpace.

The expansion was granted despite mixed data in January 2025 that showed no significant advantage to Auvelity over placebo in terms of agitation scores, the primary endpoint of the late-stage ADVANCE trial. But the drug met its primary endpoint of lowering relapse risk in the Phase 3 ACCORD-2 study.

Despite patent hump, Ascendis continues achondroplasia ascent

The FDA signed off on Ascendis’ Yuviwel in March, but months earlier, in October 2025, BioMarin had already started bracing for impact. BioMarin markets Voxzogo, which was approved for achondroplasia in November 2021 and for years reigned as the only therapy for the disease on the market. With competitive pressures on Voxzogo’s horizon—from Yuviwel and other achondroplasia products in development—BioMarin in October abandoned a goal of hitting $4 billion in revenue in 2027.

So far, Yuviwel seems to be living up to investors’ high expectations. In the second quarter, Ascendis reported €8 million ($9.3 million) in sales for Yuviwel, which as of July 31 had reached 220 patients in the U.S. since the April launch. “Early uptake is strong,” H.C. Wainwright wrote on Aug. 27.

“Voxzogo built a blockbuster market that Yuviwel only needs to convert,” the firm added. This could prove to be a relatively simple task for Ascendis, given Yuviwel’s convenience edge. While Voxzogo is given daily, Yuviwel is a weekly injection.

“Yuviwel has a stronger competitive profile than Voxzogo,” Leerink Partners said in an Aug. 18 note. “Weekly-versus-daily is a genuine convenience edge over BioMarin.”

Last month, however, BioMarin was able to eke out a victory against Ascendis in a settlement agreement that gives BioMarin 18% to 20% royalties on net Yuviwel sales through May 20, 2030. BioMarin in early 2025 filed a complaint alleging that Ascendis infringed on a European patent for Voxzogo.

The settlement will allow BioMarin to “participate economically in Yuviwel’s commercial success,” William Blair wrote on Aug. 31, but the market is still likely to shift in Ascendis’ favor.

https://www.biospace.com/business/5-biotechs-braving-the-commercial-waters-with-product-launches